All Categories
Featured

Securing Final Expense Protection for Families
Table of Contents
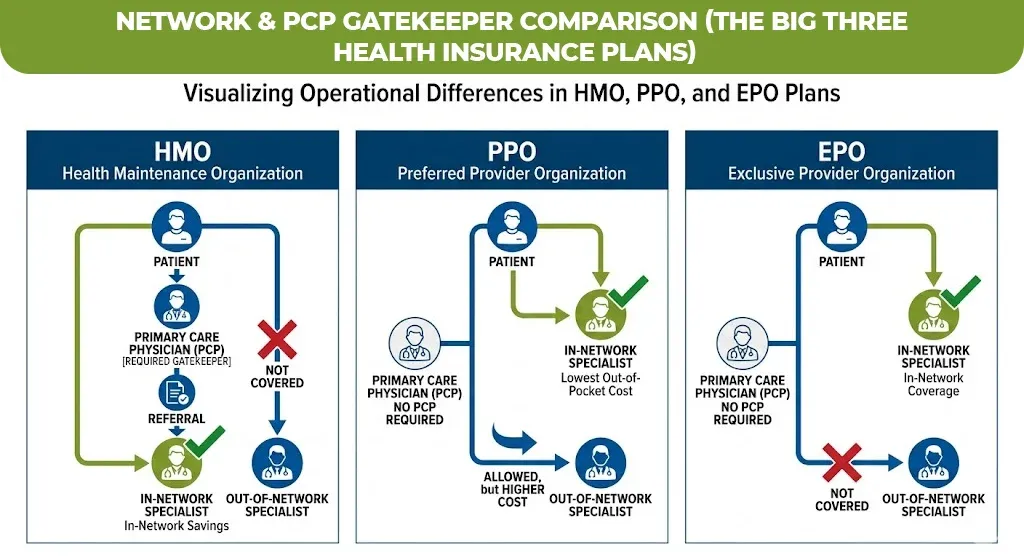
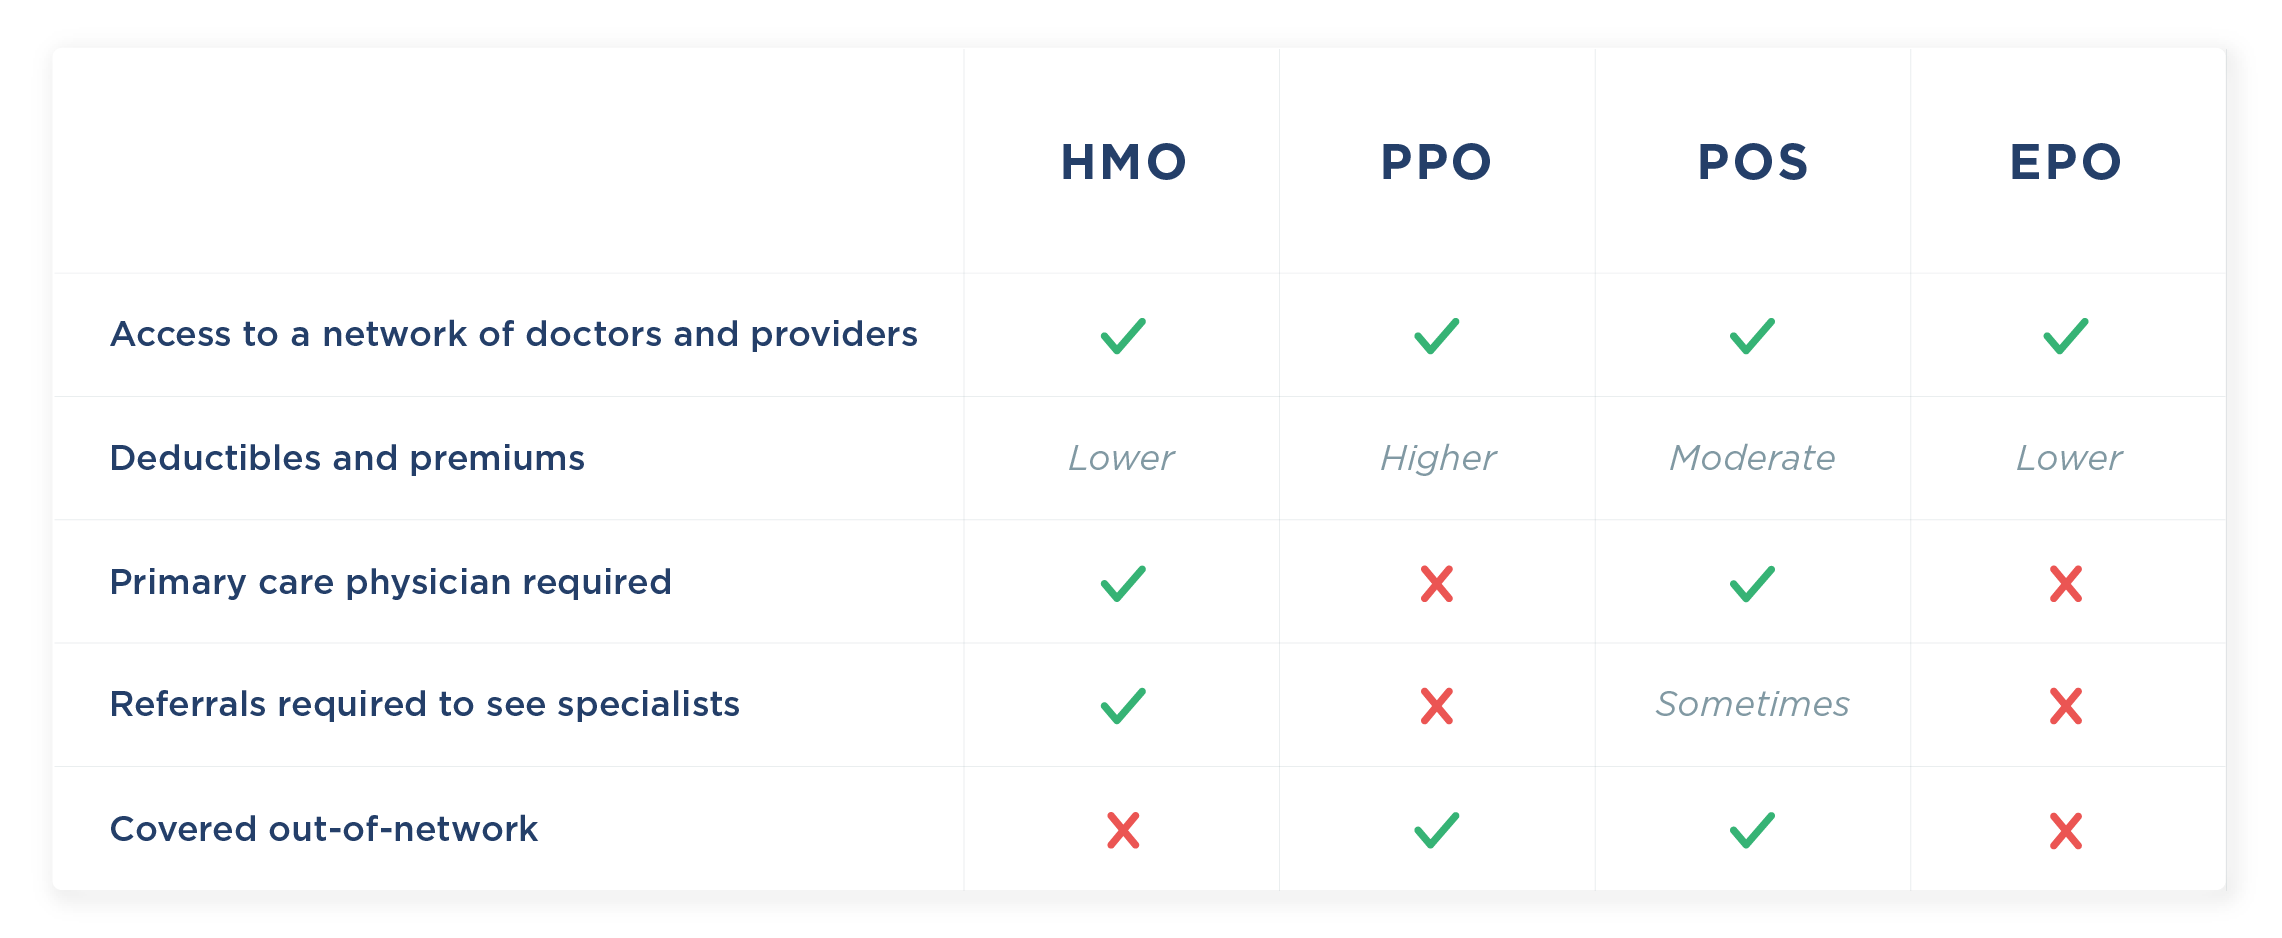
An HMO insurance coverage plan is often considered being more cost-efficient due to its lower month-to-month premiums and practical due to its requirement that clients need to have a medical care doctor to handle their care. A PPO insurance coverage plan is understood for its versatility as it permits clients to handle their own care and seek out numerous providers/specialists without needing a recommendation.
Similar to general insurance coverage strategies, the two main Medicare Advantage strategies are HMO and PPO.While HMO and PPO insurance coverage plans continue to be the most common choice for clients to select from, there are a variety of other insurance alternatives. HMO and PPO insurance strategies are the two most typical health care insurance coverage plans in the United States.
While these insurance coverage plans are different, they are similar in the sense that they provide a patient with a network of doctors, health centers, and other doctor that help members with their health-care journey. "HMO" serves as an acronym for "Health Maintenance Company," while "PPO" works as an acronym for "Preferred Service Provider Company." An HMO insurance coverage strategy is focused around a variety of health centers and healthcare suppliers (described as an "HMO network") that have agreed to treat patients within the network's insurance coverage strategy. A referral is needed for a patient to see other professionals that are in-network or out-of-network, and typically, receiving out-of-network care only takes place in emergency circumstances. However, this strategy uses lower monthly premiums for its consumers, making it a cost-efficient insurance option. Low month-to-month premiums. Not as numerous claims to submit due to in-network care.
Typically, lower expenses for prescriptions. A client can only see companies within the plan's network unless they have a referral for an outdoors professional, or it's an emergency circumstance. Like an HMO strategy, a PPO insurance strategy supplies a patient with a network (described as a "PPO network") of healthcare providers and health centers.
Smart Financial Security with Life Insurance
This plan likewise lets the client collaborate their care and manage which providers they wish to see, versus having a primary care doctor. The patient has more versatility with which service providers they choose to see, whether they're within the plan's network or out-of-network. A lot of times, there is no need for a referral if a patient cares to see an out-of-network expert.
The client is accountable for handling their healthcare, vice a main care physician supervising. A 'service provider network' refers to the list of medical professionals, professionals, healthcare facilities, and so on that an insurance coverage firm contracts to supply medical services to its plan members. Providers that are 'in-network' refer to the health care employees and hospitals that are noted in the strategy.
Insurance in Stanton CAThe costs associated with an HMO plan include deductibles, which is the quantity a patient need to pay before insurance coverage contributions, and regular monthly premiums, which is the amount taken out of a client's paycheck. Typically, the regular monthly premiums taken out with an HMO strategy are lower than a PPO plan's premiums.

Annually, this led to a $6,869 coverage on individuals and $19,445 coverage on families, showing a lower monthly premium in contrast to a PPO strategy type. Many times, the month-to-month premiums are taken out with a PPO plan that is more costly than an HMO plan's premiums.
Why Term Life Protects Family Wealth
According to the Kaiser Household Structure 2018 Health Benefits Study, all companies using a PPO insurance coverage plan paid $592 as the month-to-month premium on a specific and $1,694 as the month-to-month premium on a family. Each year, this led to a $7,149 protection on individuals and $20,324 protection on households, showing a higher month-to-month premium in contrast to an HMO plan type.
When trying to decide which strategy is best, there are many aspects to think about, with a few of the most essential being flexibility, expense performance, and coordination of care. If it's versatility that is most essential, then a PPO insurance plan might be a much better fit for they enable a patient to have more control over which service providers they see and when, no matter a recommendation.
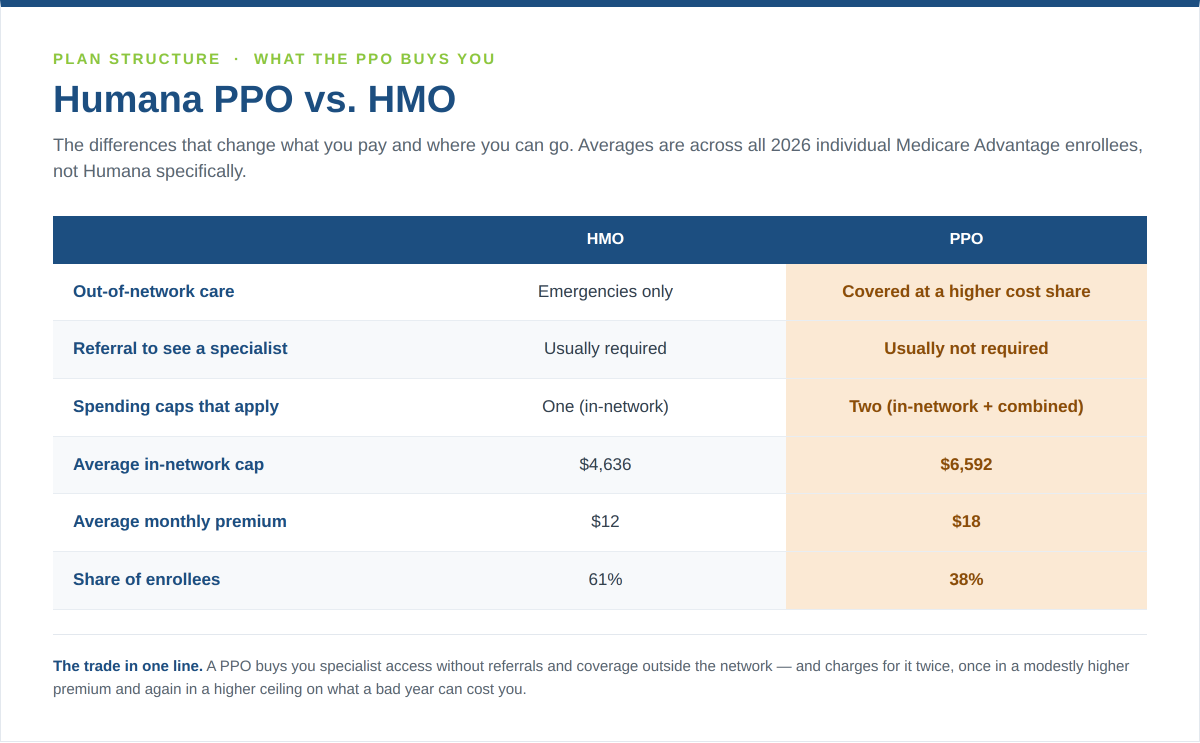
Another benefit to an HMO strategy is that it needs a patient to have a medical care physician that coordinates their care for them. This means that with a PPO insurance coverage plan, the patient will need to handle their own care and oversee which providers/specialists they require to visit. In the end, one plan is ruled out better than the other.
Medical insurance plans do not cover oral insurance. For additional information on acquiring a dental strategy, such as an oral HMO strategy, 'DHMO strategy,' or an oral PPO strategy, 'DPPO plan,' visit this resource. When an American (who has been paying Medicare taxes for a minimum of 10 years) turns 65, they certify for the medical insurance strategy understood as Medicare.

Latest Posts
Optimizing Indexed Universal Life Growth Potential in Retirement

Reviewing Term and Whole Plans
Maximizing Your Security With IUL Benefits